Common Mistakes When Calculating Salary Tax
Gusti Ayu Tita P
14 Agustus 2026
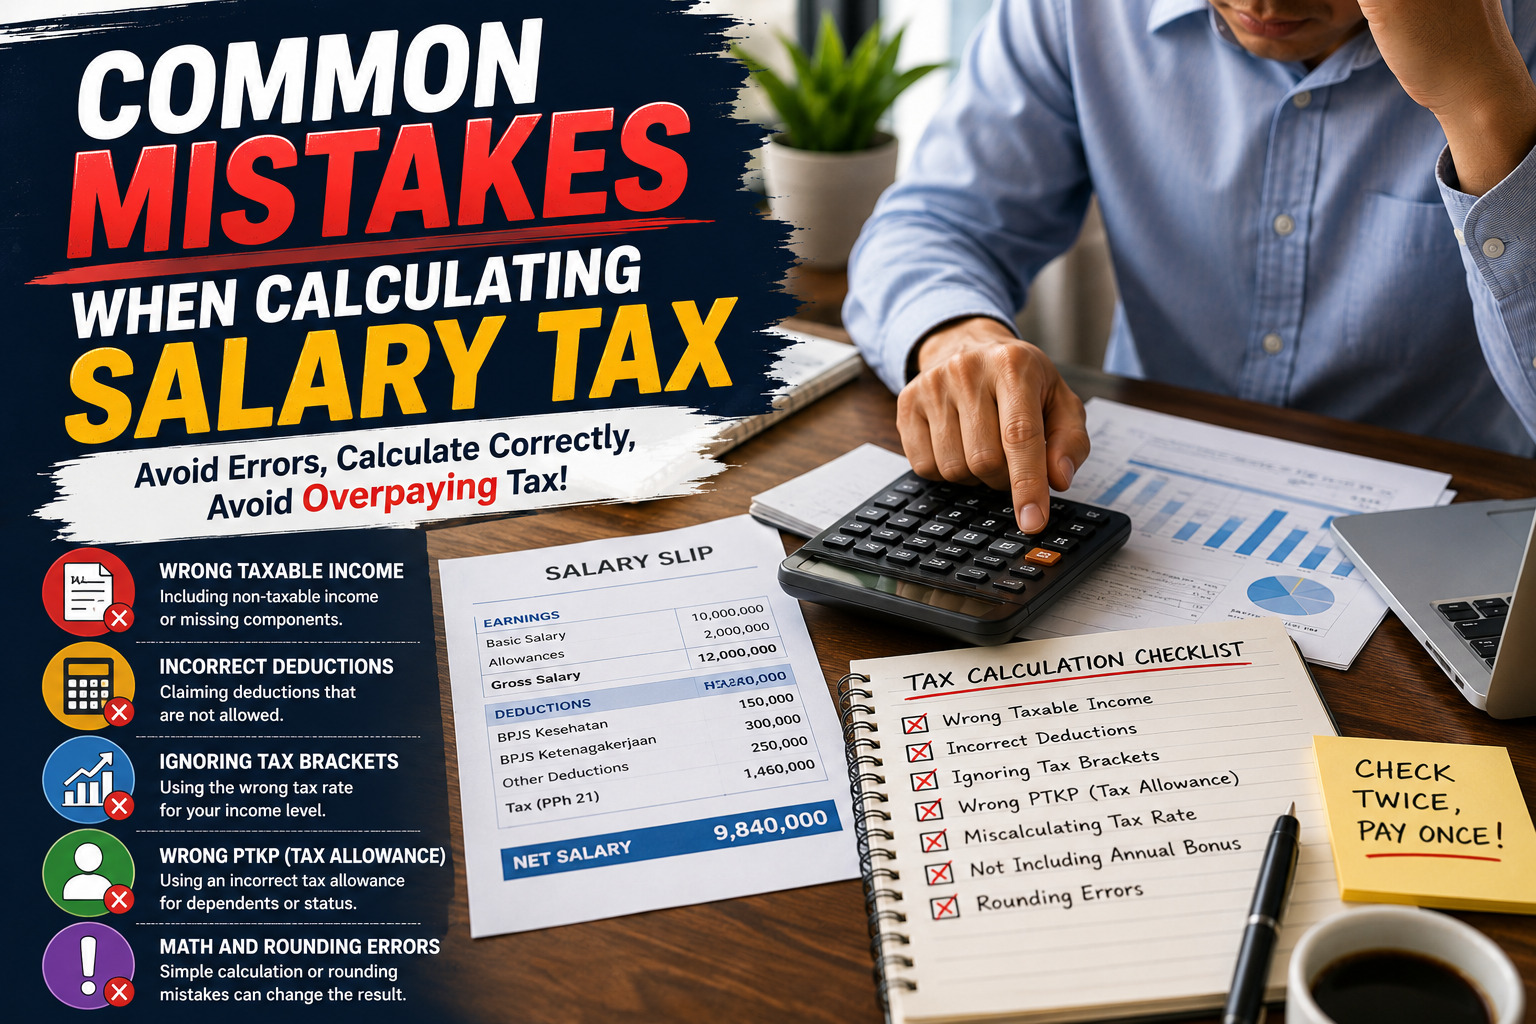
Salary tax calculation requires accuracy because mistakes can affect the amount of tax withheld from an employee's income. In Indonesia, employment-related income is generally subject to Article 21 Income Tax or PPh 21, which is calculated according to applicable tax provisions.
Errors can occur because of incorrect income data, an inaccurate tax status, or the use of an inappropriate calculation method. Understanding these common mistakes can help employees and employers reduce payroll errors and ensure that tax deductions are calculated properly.
INCORRECT GROSS INCOME
One common mistake is failing to record all components of gross employment income. Gross income may include basic salary, allowances, bonuses, incentives, and other employment-related payments that are subject to PPh 21 under applicable regulations.
Leaving out taxable income can result in an incorrect tax deduction. Employers should therefore review all payroll components before calculating PPh 21. Employees can also compare their payslips with their actual salary and additional payments to identify discrepancies.
WRONG TAX STATUS
Another common mistake is using an incorrect PTKP status. An employee's personal and family circumstances can affect the PTKP status used for determining the applicable TER category for permanent employees.
Changes in marital status or qualifying dependents should be properly recorded in payroll and tax administration. If outdated information is used, the employer may apply an inappropriate TER category. Employees should therefore ensure that their relevant personal tax information is accurate.
USING THE WRONG TAX RATE
A calculation can also be incorrect when the employer or employee uses the wrong effective rate. For permanent employees, the TER system uses Categories A, B, and C, with different rates depending on the employee's status and gross monthly income.
For example, an employee with TK/0 status and gross monthly income of IDR 8,000,000 falls within a TER Category A bracket with an effective rate of 1.50 percent. The example monthly withholding would be IDR 8,000,000 × 1.50 percent = IDR 120,000. Using a rate from the wrong category or income bracket could produce an inaccurate result.
ASSUMING TAX IS THE SAME EACH MONTH
Some employees assume that their monthly tax deduction should always be identical. This is not necessarily true because salary, bonuses, allowances, incentives, and other taxable income can change from month to month.
Another important point is the final tax period. For permanent employees, the final period uses an annual tax calculation rather than simply repeating the monthly TER calculation. Therefore, a different tax deduction in the final month does not automatically mean that an error has occurred.
CONCLUSION
Common mistakes when calculating salary tax include recording gross income incorrectly, using an outdated PTKP status, applying the wrong TER category or rate, and assuming that monthly tax deductions must always be identical.
Employees and employers can reduce these mistakes by checking gross income, personal tax information, applicable TER rates, and payroll records carefully. Understanding the difference between monthly withholding and the final annual tax calculation is also important for maintaining accurate PPh 21 administration.
About the Author
Gusti Ayu Tita P
Author — STEKOM University
An active author focused on academic issues, educational technology, and human resource development in the campus environment.