The Impact of a Hedonistic Lifestyle on Young People’s Financial Conditions
Gusti Ayu Tita P
8 September 2026
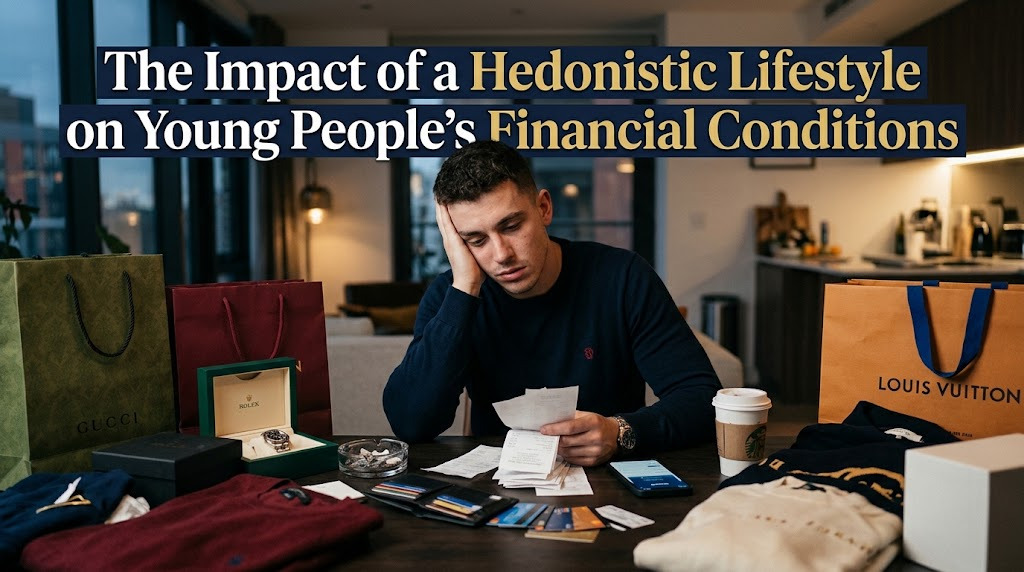
The hedonistic lifestyle among young people is increasingly associated with spending money on entertainment, fashion, food, travel, technology, and other forms of personal enjoyment. Modern digital platforms make these activities easier because products and services can be accessed within seconds. Enjoying life is not necessarily harmful, but problems can occur when pleasure and consumption become more important than financial responsibilities. If this pattern continues for a long time, it may affect savings, debt, financial planning, and future opportunities.
UNDERSTANDING HEDONISTIC CONSUMPTION
A hedonistic lifestyle is a pattern of behavior that places considerable importance on pleasure, comfort, and immediate satisfaction. Young people may demonstrate this lifestyle by frequently purchasing things they want, eating at trendy restaurants, traveling, attending entertainment events, or upgrading electronic devices. These activities can be perfectly reasonable when they are planned and affordable. The difficulty begins when spending becomes excessive or is used primarily to obtain temporary emotional satisfaction.
In the digital era, consumer behavior can change quickly because young people are constantly exposed to new products and lifestyle trends. Social media content can make certain purchases appear essential even when they are not related to basic needs. Online shopping also makes it easier to spend money without physically visiting a store. Consequently, the combination of convenience, advertising, and social influence can encourage more frequent consumption.
HOW HEDONISTIC HABITS AFFECT DAILY SPENDING
One of the most immediate effects of a hedonistic lifestyle is an increase in daily expenses. Small purchases such as coffee, snacks, online shopping, entertainment subscriptions, or food delivery may seem insignificant individually. However, repeated spending can consume a considerable portion of monthly income. When these expenses are not monitored, young people may reach the end of the month with little money remaining.
Another concern is impulsive spending. A person may purchase something because it is discounted, trending, or recommended by an influencer rather than because it is genuinely needed. Flash sales and limited-time promotions can create a sense of urgency that encourages quick decisions. Without a clear spending limit, these purchases can gradually become regular habits. Over time, uncontrolled small expenses can have a noticeable effect on overall financial health.
THE EFFECT ON SAVINGS AND EMERGENCY FUNDS
A hedonistic lifestyle can make it difficult for young people to build personal savings. When most income is allocated to entertainment and lifestyle expenses, saving may become something that is postponed until later. Unfortunately, unexpected expenses can occur at any time, including repairs, education costs, family needs, or temporary income reductions. Without an adequate emergency fund, such situations can create financial stress.
Saving is important because it provides a financial cushion and supports future goals. Young people may want to save for further education, a home, a business, travel, or other significant plans. Excessive consumption can delay these goals because money that could have been saved is repeatedly used for short-term enjoyment. Developing the habit of saving before spending can help create stronger financial security.
THE RISK OF DEBT AND FINANCIAL PRESSURE
Excessive spending can become more serious when young people use credit or debt to maintain a desired lifestyle. Buying products through installment plans or using credit facilities may make expensive purchases feel more affordable in the short term. However, the total financial obligation still needs to be paid in the future. If multiple payments accumulate, monthly income can become increasingly restricted.
Financial pressure can also arise when someone spends beyond their actual income. A person may try to maintain the same lifestyle as friends or social media personalities even though their financial circumstances are different. This can lead to borrowing money or delaying essential payments. Therefore, understanding living within one's means is an important part of responsible financial behavior.
THE IMPACT ON LONG-TERM FINANCIAL PLANNING
Financial planning requires people to consider both present needs and future goals. A person needs to think about income, expenses, savings, emergency funds, and other financial priorities. A heavily hedonistic lifestyle can make this difficult because immediate enjoyment may consistently receive more attention than long-term objectives. As a result, important financial milestones may be delayed.
Young people can reduce this risk by creating realistic financial priorities. Essential expenses should be separated from entertainment and non-essential purchases. A monthly budget can then allocate a reasonable amount for leisure while protecting savings and other important commitments. This approach allows individuals to enjoy their income without sacrificing long-term financial goals.
BUILDING HEALTHIER FINANCIAL HABITS
Changing financial behavior does not require young people to stop enjoying themselves completely. Instead, they can practice balanced spending by setting limits for entertainment, shopping, dining, and other lifestyle activities. Comparing prices, avoiding unnecessary purchases, and waiting before making expensive decisions can reduce impulsive behavior. Tracking expenses can also reveal where money is being spent and which habits may need adjustment.
Another important habit is learning to distinguish between needs and wants. Needs are expenses required for basic living and important responsibilities, while wants are purchases that provide additional comfort or enjoyment. Understanding this difference can make financial decisions more intentional. With consistent budgeting and saving, young people can enjoy their current lifestyle while gradually building stronger financial stability.
CONCLUSION
The impact of a hedonistic lifestyle on young people's financial conditions can be significant when spending becomes excessive and uncontrolled. Frequent purchases, entertainment expenses, social pressure, and impulsive consumption can reduce savings and increase financial obligations. In more serious situations, these habits may contribute to debt and make long-term financial goals more difficult to achieve.
However, enjoying life and maintaining financial responsibility can exist together. Young people can set spending limits, build savings, monitor expenses, and prioritize important financial goals while still allocating money for entertainment. The key is developing financial discipline and conscious consumption rather than completely rejecting enjoyable experiences. With a balanced approach, young people can enjoy the present while creating a more secure financial future.
About the Author
Gusti Ayu Tita P
Author — STEKOM University
An active author focused on academic issues, educational technology, and human resource development in the campus environment.