What Percentage of Salary Is Taxed and How Is It Calculated?
Gusti Ayu Tita P
14 Agustus 2026
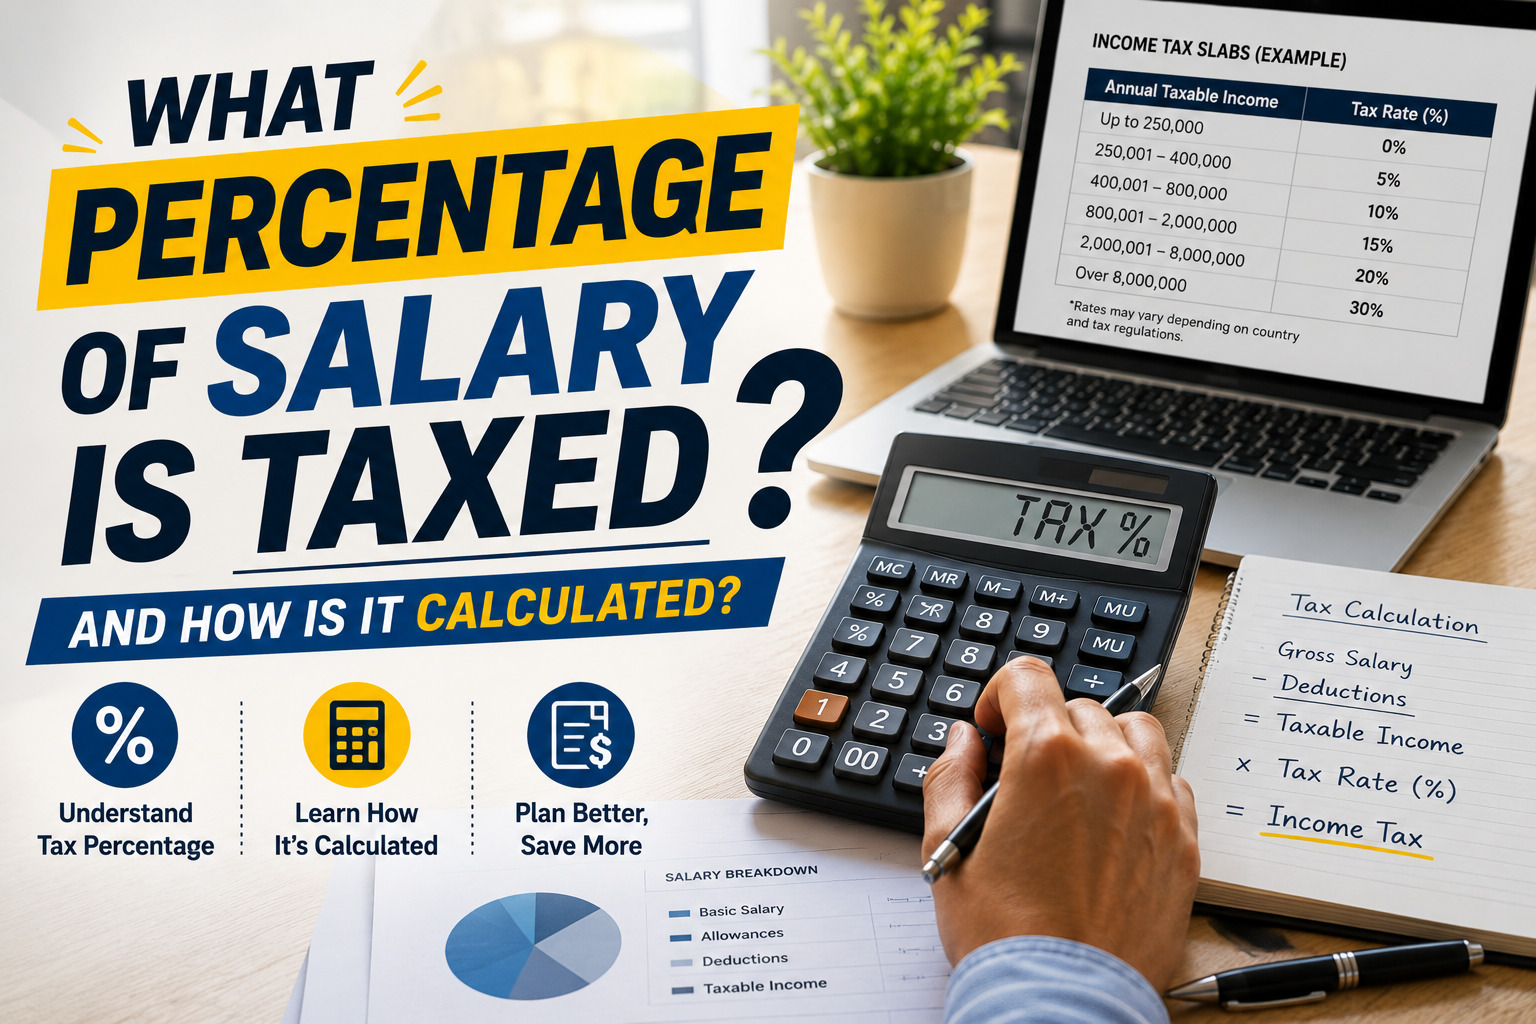
Salary tax percentage is not necessarily the same for every employee in Indonesia. The amount of tax withheld from salary depends on factors such as gross monthly income, employee status, and applicable tax rates.
For employees, salary-related income is generally subject to Article 21 Income Tax or PPh 21. Understanding the applicable percentage helps employees estimate their monthly tax deduction and better understand the information shown on their payslip.
HOW MUCH SALARY IS TAXED?
There is no single percentage that applies to every employee. For permanent employees, monthly PPh 21 withholding during tax periods other than the final tax period uses the Average Effective Rate or TER. The applicable rate is determined based on gross monthly income and the employee's relevant TER category.
The TER system has Categories A, B, and C, which are related to the employee's PTKP status. Each category contains different income brackets with different effective rates. Therefore, employees with different income levels or tax statuses may have different monthly tax deductions.
FACTORS THAT DETERMINE THE RATE
The first important factor is gross monthly income. Gross income can include salary, allowances, bonuses, incentives, and other employment-related payments that are subject to PPh 21 under the applicable rules. A higher gross income can place an employee in a different effective-rate bracket.
The employee's PTKP status also affects the applicable TER category. For example, certain unmarried employee statuses are included in Category A, while some other family and dependent statuses fall under Categories B or C. Employees should make sure their personal information is recorded correctly by their employer.
EXAMPLE OF TAX CALCULATION
For example, an employee with TK/0 status receives gross monthly income of IDR 8,000,000. Under TER Category A, this income falls within the bracket with an effective rate of 1.50 percent.
The calculation is IDR 8,000,000 × 1.50 percent = IDR 120,000. Therefore, the example monthly PPh 21 withholding is IDR 120,000. This means the employee would have IDR 7,880,000 remaining after this tax deduction alone, before other applicable payroll deductions.
MONTHLY AND ANNUAL TAX DIFFERENCES
Employees should not assume that the monthly tax amount can simply be multiplied by twelve to determine their annual tax liability. For permanent employees, the TER is generally used for monthly withholding during tax periods other than the final tax period.
In the final tax period, PPh 21 is recalculated based on the employee's annual income and the applicable annual tax provisions. As a result, the tax withheld in the final month may be different from the amounts withheld in previous months. The monthly TER system is designed to simplify withholding rather than replace the annual tax calculation.
CONCLUSION
Salary tax percentage in Indonesia varies according to the employee's gross income and applicable tax status. For permanent employees, monthly PPh 21 withholding generally uses TER Categories A, B, or C, with the specific rate determined by the relevant income bracket.
Employees can estimate their monthly tax by identifying their gross salary, PTKP status, TER category, and effective rate. However, the final tax period uses an annual calculation, so monthly withholding should not be treated as the final annual tax amount.
About the Author
Gusti Ayu Tita P
Author — STEKOM University
An active author focused on academic issues, educational technology, and human resource development in the campus environment.