How to Adjust Your Monthly Budget When Your Income Changes?
Gusti Ayu Tita P
6 Agustus 2026
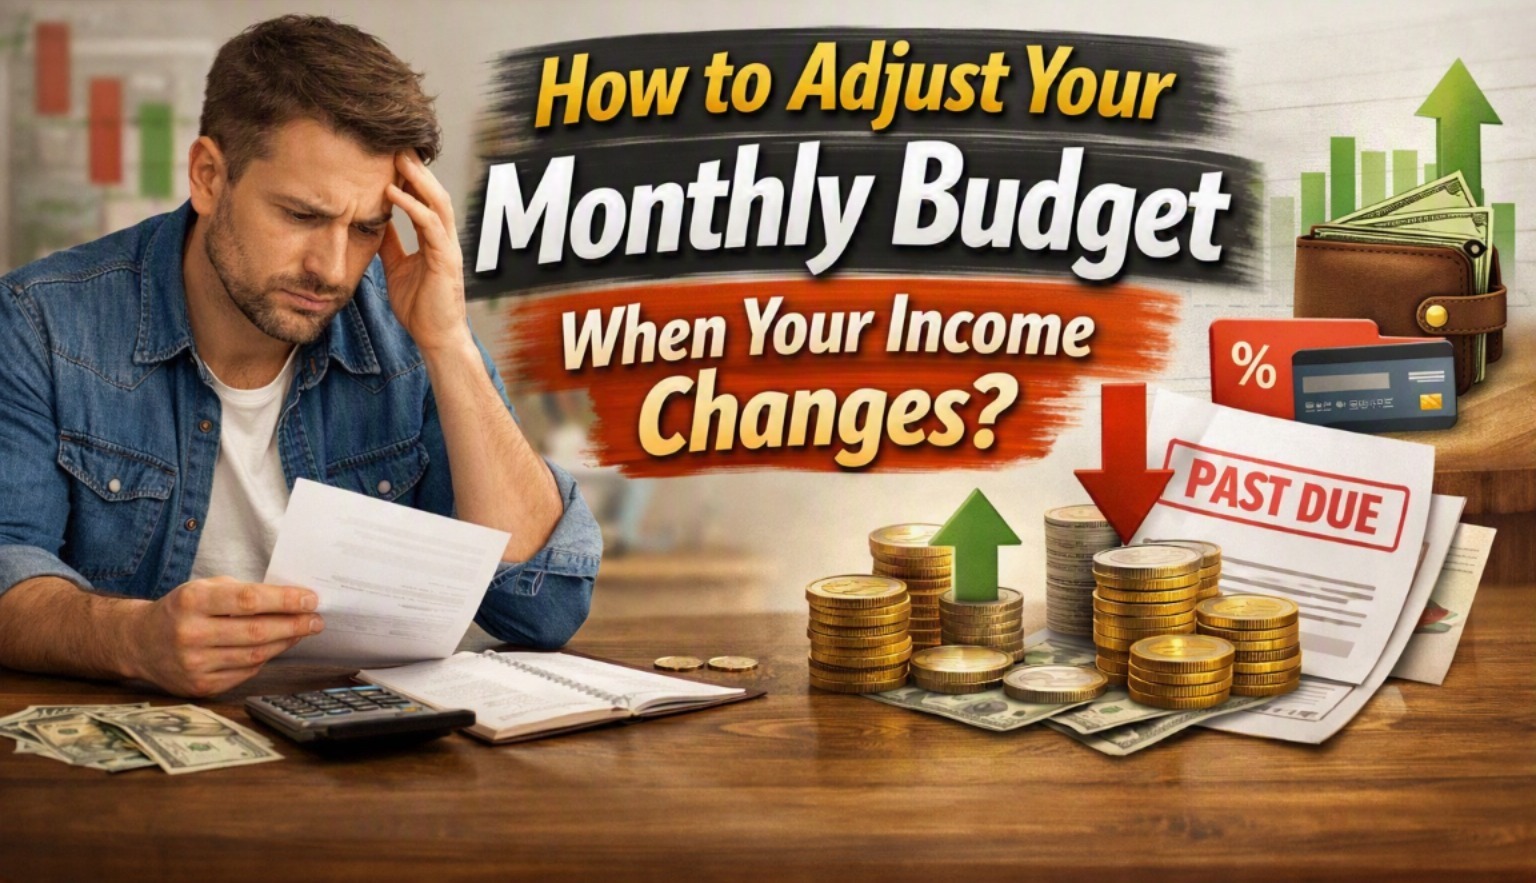
Managing your finances becomes more challenging when your income increases or decreases unexpectedly. A monthly budget should never remain static because your financial situation can change due to a new job, reduced working hours, business performance, bonuses, or unexpected expenses. Adjusting your budget quickly helps you stay in control and avoid financial stress. By making thoughtful changes, you can continue meeting your financial goals while protecting your long-term stability.
REVIEW YOUR NEW FINANCIAL SITUATION
The first step is to understand exactly how much your income has changed. Compare your previous monthly income with your current earnings and calculate the difference. Include every reliable source of income, such as your salary, freelance work, business profits, or passive income. This provides a realistic picture of your available funds.
After calculating your income, review your essential monthly expenses. These include housing, food, transportation, utilities, insurance, and loan payments. Knowing your financial baseline makes it easier to decide where adjustments are necessary and prevents overspending.
UPDATE YOUR ESSENTIAL AND NON ESSENTIAL EXPENSES
A changing income means your spending plan should also change. Start by separating essential expenses from non-essential expenses. Essential expenses cover your daily needs, while non-essential spending includes entertainment, dining out, shopping, and luxury purchases.
If your income decreases, reduce discretionary spending before cutting important necessities. If your income increases, avoid immediately increasing your lifestyle. Instead, allocate additional income toward savings, investments, or paying off debt before increasing optional spending.
PRIORITIZE SAVINGS AND EMERGENCY FUNDS
No matter how your income changes, maintaining a consistent savings habit is essential. Even if you can only save a small amount during difficult months, regular saving builds long-term financial discipline.
When your income increases, consider directing a significant portion toward an emergency fund. Financial experts generally recommend saving enough to cover several months of living expenses. This emergency reserve provides security if your income unexpectedly decreases again in the future.
ADJUST YOUR FINANCIAL GOALS
Changes in income often require changes in your financial goals. If your income decreases, you may need to postpone certain purchases or extend the timeline for achieving larger goals. This adjustment is not a failure but a practical response to changing circumstances.
If your income increases, use the opportunity to accelerate your financial progress. You may be able to pay off loans faster, invest more consistently, or increase retirement contributions. Updating your goals keeps your budget aligned with your current financial capacity.
TRACK YOUR SPENDING EVERY MONTH
A budget only works if you actively monitor it. Record your spending regularly using a notebook, spreadsheet, or budgeting application. Tracking expenses allows you to identify unnecessary purchases and maintain better financial control.
Review your budget at the end of every month and compare planned expenses with actual spending. This monthly review helps you recognize patterns, improve future budgeting decisions, and make adjustments before small financial problems become larger ones.
BUILD FLEXIBILITY INTO YOUR BUDGET
A flexible budget is more effective than a rigid one because life is unpredictable. Unexpected medical bills, home repairs, or family emergencies can affect your finances at any time. Including a buffer in your monthly budget reduces the impact of these unexpected costs.
Avoid allocating every dollar of income to planned expenses. Keeping some money unassigned provides flexibility and helps you respond to financial changes without relying on debt or credit cards.
AVOID EMOTIONAL SPENDING DURING INCOME CHANGES
Income changes often trigger emotional reactions. Some people spend more after receiving a raise, while others make panic decisions after a reduction in income. Both situations can damage long-term financial stability.
Instead, make financial decisions based on your updated budget rather than emotions. Waiting a few days before making major purchases and reviewing your financial priorities can help prevent unnecessary spending and improve money management.
CONCLUSION
Adjusting your monthly budget when your income changes is one of the most important financial habits you can develop. A flexible budget allows you to respond confidently to both income increases and decreases without sacrificing financial stability. By reviewing your income, updating expenses, prioritizing savings, tracking spending, and avoiding emotional decisions, you can maintain control over your finances. Consistent budgeting ensures that every financial change becomes an opportunity to strengthen your long-term financial future.
Tentang Penulis
Gusti Ayu Tita P
Penulis — Universitas STEKOM
Penulis aktif yang berfokus pada isu-isu akademik, teknologi pendidikan, dan pengembangan sumber daya manusia di lingkungan kampus.