
How to Calculate Tax From Monthly Salary?
Gusti Ayu Tita P
14 Agustus 2026
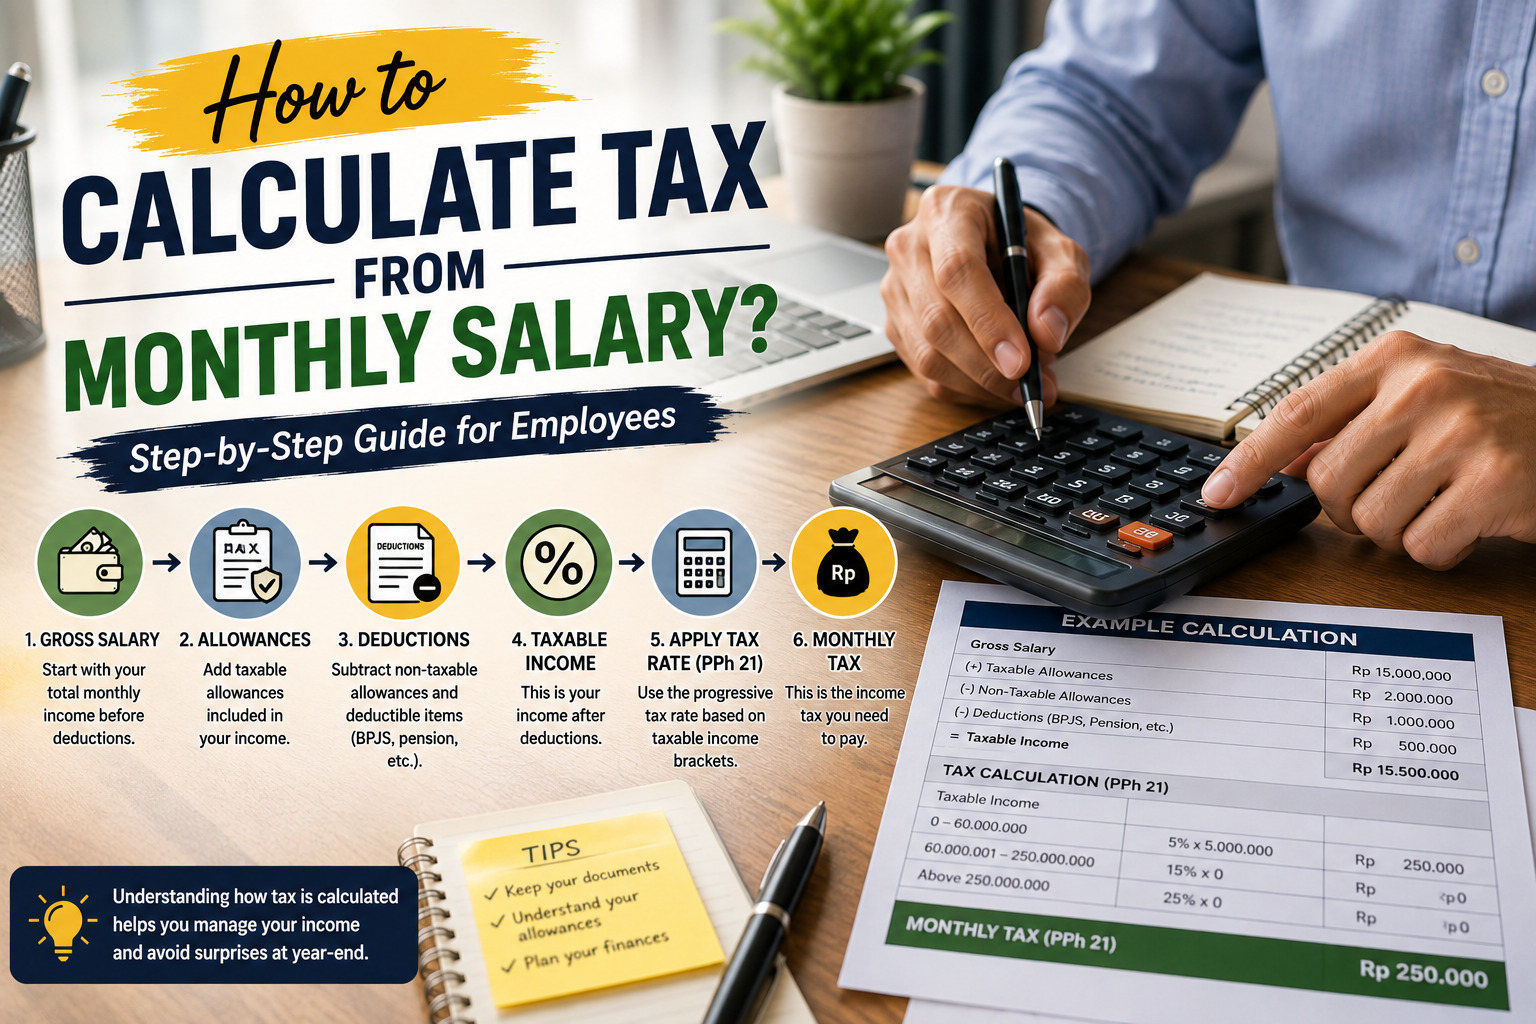
Calculating tax from monthly salary helps employees understand how much income tax is deducted from their earnings each month. In Indonesia, salary-related income is generally subject to Article 21 Income Tax or PPh 21, which is commonly withheld by the employer.
Understanding the calculation does not have to be complicated. Employees can start by identifying their gross monthly income, checking their tax status, and determining the applicable effective rate. This makes it easier to understand the tax deduction shown on a payslip.
IDENTIFY GROSS MONTHLY INCOME
The first step is to determine the employee's gross monthly income. Gross income refers to employment income before applicable tax and other payroll deductions are taken into account. It can include basic salary, allowances, bonuses, incentives, and other taxable employment-related payments.
The gross amount may change from month to month. For example, an employee who receives a bonus or additional allowance may have higher gross income in that month. Because the tax calculation can be affected by gross income, employees should review every component listed on their payslip.
CHECK THE TAX STATUS
The next step is to check the employee's PTKP or Non-Taxable Income status. This status is related to personal and family circumstances, including marital status and qualifying dependents under the applicable rules.
For permanent employees, PTKP status helps determine the applicable TER Category A, B, or C. Each category has different effective-rate brackets. Therefore, employees should make sure their tax information is recorded correctly by their employer.
APPLY THE EFFECTIVE RATE
For permanent employees, the Average Effective Rate or TER is generally used for PPh 21 withholding during tax periods other than the final tax period. The applicable percentage depends on the employee's gross monthly income and TER category.
For example, an employee with TK/0 status receives gross monthly income of IDR 8,000,000. Under TER Category A, this income falls within a bracket using an effective rate of 1.50 percent. The calculation is IDR 8,000,000 × 1.50 percent = IDR 120,000, so the example monthly PPh 21 withholding is IDR 120,000.
CHECK THE FINAL TAX CALCULATION
Employees should understand that monthly withholding is not the same as final annual tax. The TER method is used to simplify monthly withholding during the applicable tax periods, but the final tax period uses an annual calculation based on the employee's total income and applicable tax provisions.
Because of this, the amount withheld in the final tax period can be different from previous months. Employees should not simply multiply one month's tax deduction by twelve to determine their final annual tax. The annual calculation is needed to determine the actual tax liability and reconcile previous withholdings.
CONCLUSION
How to calculate tax from monthly salary can be understood by identifying gross income, checking PTKP status, and applying the appropriate TER. For permanent employees, this method generally applies during tax periods other than the final tax period.
Employees should regularly check their payslips, gross salary, tax deductions, and personal tax information. Understanding these components makes it easier to see how PPh 21 affects monthly income and why tax deductions may vary between months.
Tentang Penulis
Gusti Ayu Tita P
Penulis — Universitas STEKOM
Penulis aktif yang berfokus pada isu-isu akademik, teknologi pendidikan, dan pengembangan sumber daya manusia di lingkungan kampus.















