KUR Mandiri for MSMEs Smart Strategies to Get Business Capital Without Disrupting Cash Flow
Gusti Ayu Tita P
21 Agustus 2026
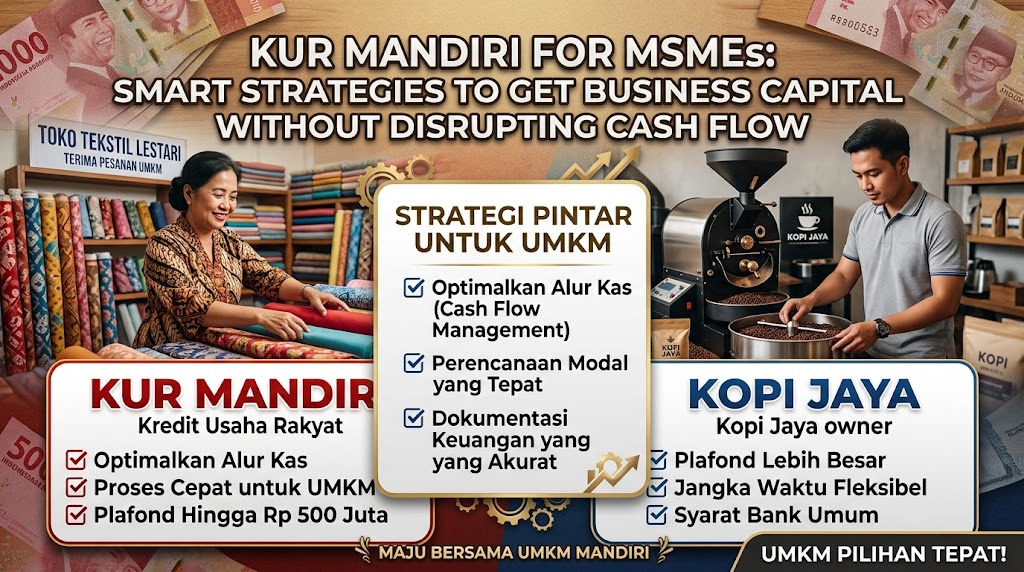
For Micro Small and Medium Enterprises or MSMEs, additional capital can create opportunities to increase inventory, improve production, purchase equipment, or expand operations. However, taking business financing without proper planning can put pressure on cash flow and make daily operations more difficult. KUR Mandiri can be considered by eligible entrepreneurs who need financing for productive business activities. The key is to obtain financing according to actual needs and manage the funds carefully.
UNDERSTAND YOUR ACTUAL BUSINESS CAPITAL NEEDS
Before applying for KUR Mandiri, entrepreneurs should calculate how much additional capital their business really needs. Start by identifying productive expenses such as inventory, raw materials, equipment, or other costs related to business development. Compare the total requirement with the capital already available in the business. This calculation can help prevent entrepreneurs from borrowing more than necessary.
A realistic financing plan should also consider the business's current cash flow. If the business has irregular revenue, the owner should use conservative estimates rather than assuming that sales will always increase. The financing amount should be appropriate for the size and condition of the business. Borrowing only what the business can reasonably manage can reduce unnecessary financial pressure.
CHOOSE PRODUCTIVE USES FOR KUR FUNDS
One of the most important strategies is to use KUR financing for productive activities. Additional capital can potentially support inventory purchases, raw materials, productive equipment, or other eligible business needs. Entrepreneurs should prioritize expenses that can directly support revenue generation or improve operational efficiency. Every planned expenditure should have a clear connection to the business.
For example, a retailer may need additional inventory because customer demand has increased, while a small producer may need productive equipment to increase output. However, entrepreneurs should evaluate the expected benefit before spending the funds. Business growth should be supported by realistic demand, not assumptions. This can help ensure that borrowed capital contributes to the business rather than becoming an unnecessary expense.
KEEP BUSINESS CASH FLOW UNDER CONTROL
Maintaining healthy business cash flow is essential when using financing. Entrepreneurs should monitor money coming into the business and compare it with operating expenses and financing obligations. Regular records of sales, purchases, inventory, and expenses can make financial problems easier to identify. Even simple bookkeeping can help business owners make better decisions.
It is also useful to maintain a reasonable cash reserve for unexpected expenses. Entrepreneurs should avoid spending all available funds immediately after receiving financing. Cash flow management becomes even more important when sales fluctuate from month to month. By maintaining sufficient working cash, businesses can continue operating while meeting their financial obligations.
SEPARATE BUSINESS AND PERSONAL FINANCES
Mixing business and personal money can make it difficult to determine whether a business is genuinely profitable. Entrepreneurs should therefore separate business finances and personal finances whenever possible. Business income should be recorded separately from personal income, while business expenses should be clearly identified. This makes it easier to monitor the use of KUR funds.
Business owners should also avoid using financing for unnecessary personal purchases. The money should remain focused on its intended productive business purpose. Regularly reviewing financial records can help entrepreneurs identify whether funds are being used as planned. Good financial discipline can protect both business operations and repayment capacity.
PLAN REPAYMENT BEFORE TAKING FINANCING
An entrepreneur should calculate repayment capacity before accepting KUR financing. Expected business cash flow should be sufficient to cover operating costs and financing payments. Business owners should not rely entirely on optimistic sales projections when making this calculation. They should also consider periods when revenue may decline or unexpected expenses may occur.
Planning repayment from the beginning can prevent financing from disrupting daily operations. Entrepreneurs can include repayment obligations in their monthly business budget and monitor cash flow regularly. If business revenue increases after receiving financing, the owner should still maintain disciplined financial management. Responsible repayment is an important part of maintaining a healthy business.
CONCLUSION
KUR Mandiri for MSMEs can be a useful source of business capital for eligible entrepreneurs, but financing should be obtained and managed carefully. The most important strategies are calculating actual capital needs, using funds for productive purposes, controlling cash flow, separating personal and business finances, and planning repayment realistically. These steps can help prevent additional financing from creating unnecessary pressure on daily operations.
In conclusion, the goal of obtaining KUR Mandiri should not simply be to receive more money, but to use financing as a tool for sustainable business development. Entrepreneurs should choose a financing amount that matches their business capacity and maintain accurate financial records throughout the financing period. They should also confirm the latest KUR Mandiri requirements, financing limits, costs, and conditions directly with Bank Mandiri before applying. With disciplined planning, MSMEs can use additional capital to strengthen operations while maintaining healthier cash flow and long term business growth.
Tentang Penulis
Gusti Ayu Tita P
Penulis — Universitas STEKOM
Penulis aktif yang berfokus pada isu-isu akademik, teknologi pendidikan, dan pengembangan sumber daya manusia di lingkungan kampus.