Tips for Managing Online Loan Payments Effectively
Gusti Ayu Tita P
6 Agustus 2026
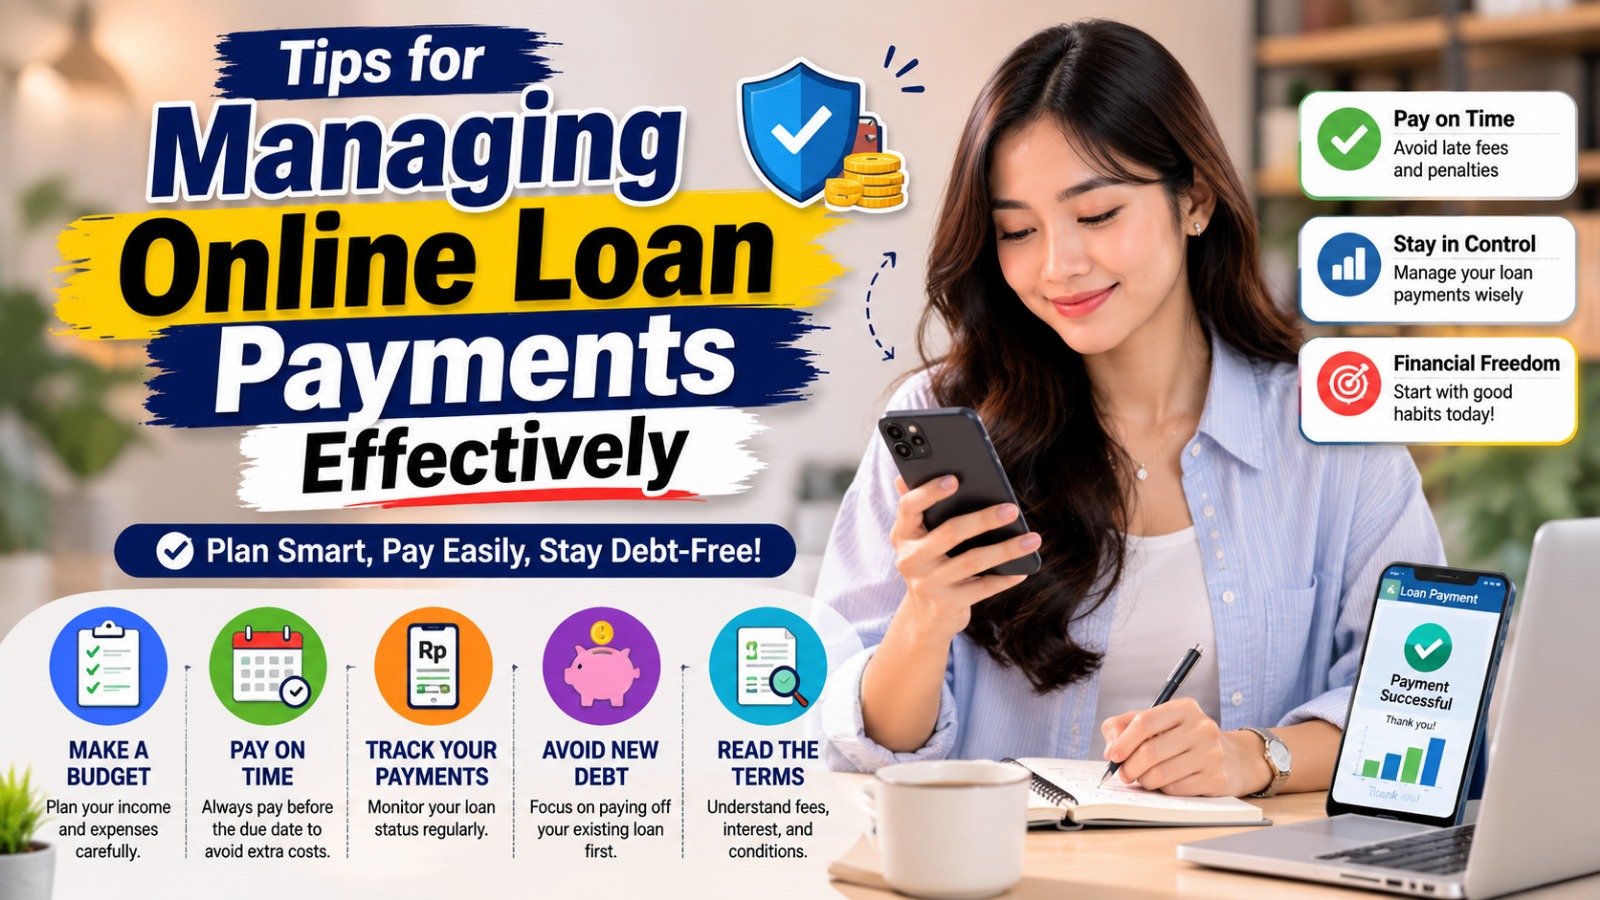
Online loans can provide convenient access to funds, but repayment needs to be managed carefully. Once a loan is approved, borrowers have a financial obligation to make payments according to the agreed schedule. Without proper planning, missed payments can create additional costs and put pressure on household finances. Therefore, effective repayment management is an important part of responsible online borrowing.
Good payment management starts before the loan is taken. Borrowers should understand the repayment amount, due date, loan costs, and repayment period. They should also consider existing financial obligations before accepting a new loan. With careful planning and consistent financial habits, online loan payments can be managed more effectively.
UNDERSTAND YOUR TOTAL REPAYMENT OBLIGATION
The first step in managing online loan payments is understanding exactly how much needs to be repaid. Do not focus only on the amount received when the loan is disbursed. Check the total repayment obligation, including applicable interest or economic benefit, service fees, administrative costs, and other charges stated in the agreement. Understanding the complete cost helps borrowers create a more accurate financial plan.
Read the loan agreement carefully before accepting the financing. Pay attention to the repayment schedule, installment amount, due dates, and consequences of late payment. If any term is unclear, seek an explanation through the provider’s official customer service channel. A clear understanding of the agreement can prevent avoidable mistakes during the repayment period.
CREATE A REALISTIC MONTHLY BUDGET
A realistic budget can make online loan payments easier to manage. Start by listing regular income and essential expenses such as food, housing, transportation, education, and utilities. Then include existing debt payments and the new online loan installment. This calculation can show whether the new financial obligation fits comfortably within the available budget.
Avoid creating a budget that leaves no room for unexpected expenses. Emergencies can occur even when monthly income is stable. Setting aside some money for essential unexpected needs can help prevent borrowers from relying on another loan. A balanced budget should cover both current obligations and reasonable financial reserves.
SET REMINDERS FOR PAYMENT DUE DATES
Forgetting a payment deadline can lead to unnecessary problems. Borrowers should record every due date in a calendar, financial application, or other reminder system. Setting reminders several days before the deadline provides time to prepare the required funds. This simple habit can reduce the possibility of accidental late payments.
It is also useful to check the payment status after making a transaction. Keep payment receipts or digital confirmations as evidence that the installment has been paid. If a payment does not appear correctly in the system, contact the provider through its official channel. Good records make it easier to track repayment progress and resolve potential discrepancies.
PRIORITIZE LOAN PAYMENTS IN YOUR BUDGET
Loan payments should be included as a regular financial obligation rather than treated as an optional expense. After receiving income, allocate the amount needed for upcoming installments before spending on less important purchases. This approach can help ensure that money intended for repayment is not accidentally used elsewhere. Consistency is particularly important when the loan has a fixed repayment schedule.
However, prioritizing debt payments does not mean ignoring essential household needs. Borrowers should maintain a reasonable balance between repayment obligations and basic living expenses. If an installment becomes too difficult to manage, reassess the overall budget rather than immediately taking another loan. Responsible financial planning should reduce debt pressure rather than increase it.
AVOID TAKING NEW LOANS TO PAY OLD DEBTS
One of the most important rules for managing online loan payments is avoiding repeated borrowing to cover previous obligations. Taking a new loan to pay an old one can create a cycle of debt. Over time, multiple repayment obligations can consume a larger part of monthly income. This can make financial recovery more difficult.
If debt payments are becoming difficult, list all current obligations and review the overall financial situation. Identify which payments are due, how much is owed, and what income is available. Avoid adding new debt until the existing obligations are under better control. If appropriate, contact the relevant provider through official channels to discuss available options.
REDUCE UNNECESSARY EXPENSES DURING REPAYMENT
Temporary spending adjustments can help borrowers maintain payment consistency. Review nonessential expenses such as impulsive shopping, unused subscriptions, or unnecessary entertainment costs. Reducing these expenses can create additional room in the monthly budget. The goal is not to eliminate every enjoyable activity but to ensure that important financial obligations remain manageable.
A simple spending plan can make this process easier. Divide expenses into essential, important, and optional categories. During periods when loan payments are due, prioritize essential expenses and limit optional spending where necessary. This approach can help borrowers stay focused on repayment without making the budgeting process unnecessarily complicated.
BUILD AN EMERGENCY FUND
An emergency fund can provide additional financial protection during the repayment period. Unexpected expenses such as urgent repairs, family needs, or temporary income disruptions can affect a borrower’s ability to pay. Even a modest reserve can provide some flexibility when unexpected costs arise. The amount saved should be realistic and based on the borrower’s financial situation.
Building an emergency fund may take time, especially when someone already has debt obligations. Start with a manageable amount rather than waiting until a large sum can be saved. Keep the money separate from everyday spending so it is available when genuinely needed. A financial reserve can also reduce the temptation to take another online loan during an emergency.
MONITOR YOUR DEBT AND FINANCIAL PROGRESS
Regular monitoring helps borrowers understand whether their financial situation is improving. Keep track of the remaining balance, payments already made, upcoming due dates, and other outstanding debts. Reviewing this information regularly can make financial obligations feel more organized and manageable. It can also help identify problems before they become serious.
Borrowers should also review their income and expenses when circumstances change. A change in employment, household costs, or other financial responsibilities may require adjustments to the budget. Avoid ignoring warning signs such as repeated payment difficulties or dependence on new borrowing. Early action is generally easier than trying to solve a larger debt problem later.
COMMUNICATE THROUGH OFFICIAL CHANNELS IF PROBLEMS OCCUR
Financial difficulties can sometimes happen despite careful planning. If a borrower expects difficulty making a payment, it is better to contact the lending provider through its official customer service channel instead of ignoring the problem. Ask about the procedures or options that may be available under the agreement. Any solution should be understood clearly before accepting new terms.
Be careful with people who claim they can settle online loan debts in exchange for unusual fees or personal information. Verify any assistance directly with the official provider. Keep copies of agreements, payment records, and important communications. Using verified communication channels can help protect borrowers from additional financial or privacy risks.
CONCLUSION
Managing online loan payments effectively requires planning, discipline, and regular monitoring. Borrowers should understand their total repayment obligations, create a realistic budget, record due dates, prioritize necessary payments, and avoid taking new loans to cover old debts. Building an emergency fund and reducing unnecessary expenses can also provide greater financial stability during the repayment period.
The most important principle is to borrow within your financial ability and treat every installment as a serious obligation. If financial difficulties arise, take action early and communicate through official channels. With responsible financial habits, borrowers can manage online loan payments more effectively while reducing the risk of unnecessary debt.
Tentang Penulis
Gusti Ayu Tita P
Penulis — Universitas STEKOM
Penulis aktif yang berfokus pada isu-isu akademik, teknologi pendidikan, dan pengembangan sumber daya manusia di lingkungan kampus.